Introduction
One of you asked me to write about housing and construction, and it's a fair request. It's also an overdue one, because I have been bullish on this industry for a while now, and we have all seen that stock prices have told me that I'm early. Or wrong.
The tough part is that the market never tells us what we're dealing with as it happens. We figure this out in hindsight.
So, let me get the uncomfortable part out of the way first.
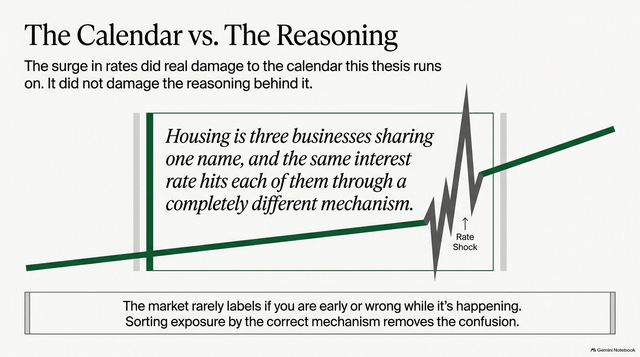
The surge in rates did real damage to my thesis. Not to the reasoning behind it, but to the calendar it runs on, which is a distinction I want to defend properly. As many of you know, "I was early" is the most abused sentence in this business. If I had a dollar for every time someone used it to avoid admitting they were simply wrong, I could fund a decent starter position in one of my favorite stocks - or finally buy a GLE 63 AMG.
Here's the thing I want you to leave with, even if you stop reading right here:
Housing is three businesses sharing one name, and the same interest rate hits each of them through a completely different mechanism.
Turnover. Repair and remodel. New construction. One of those things is frozen. One never stopped at all and is arguably being fed by the very thing that froze the first one. And one is being rebuilt from the inside while nobody watches, in ways that are changing the structure of the industry permanently.
That's super confusing, right?
However, if you sort your exposure into the right "basket," most of the confusion in this sector disappears.
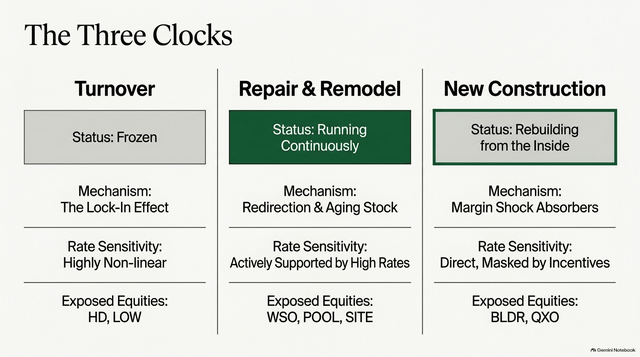
In this article, I'll walk through all three "clocks," with the names I find most interesting in each, then give you the structural case, then the part most bulls skip, which is what would actually kill this thesis.
I'll finish with where I'd get paid while waiting, and my own falsifier.
In other words, as we have a ton on our plate, let's dive in!
Sign in to leave a comment and join the discussion.
Sign Up Free