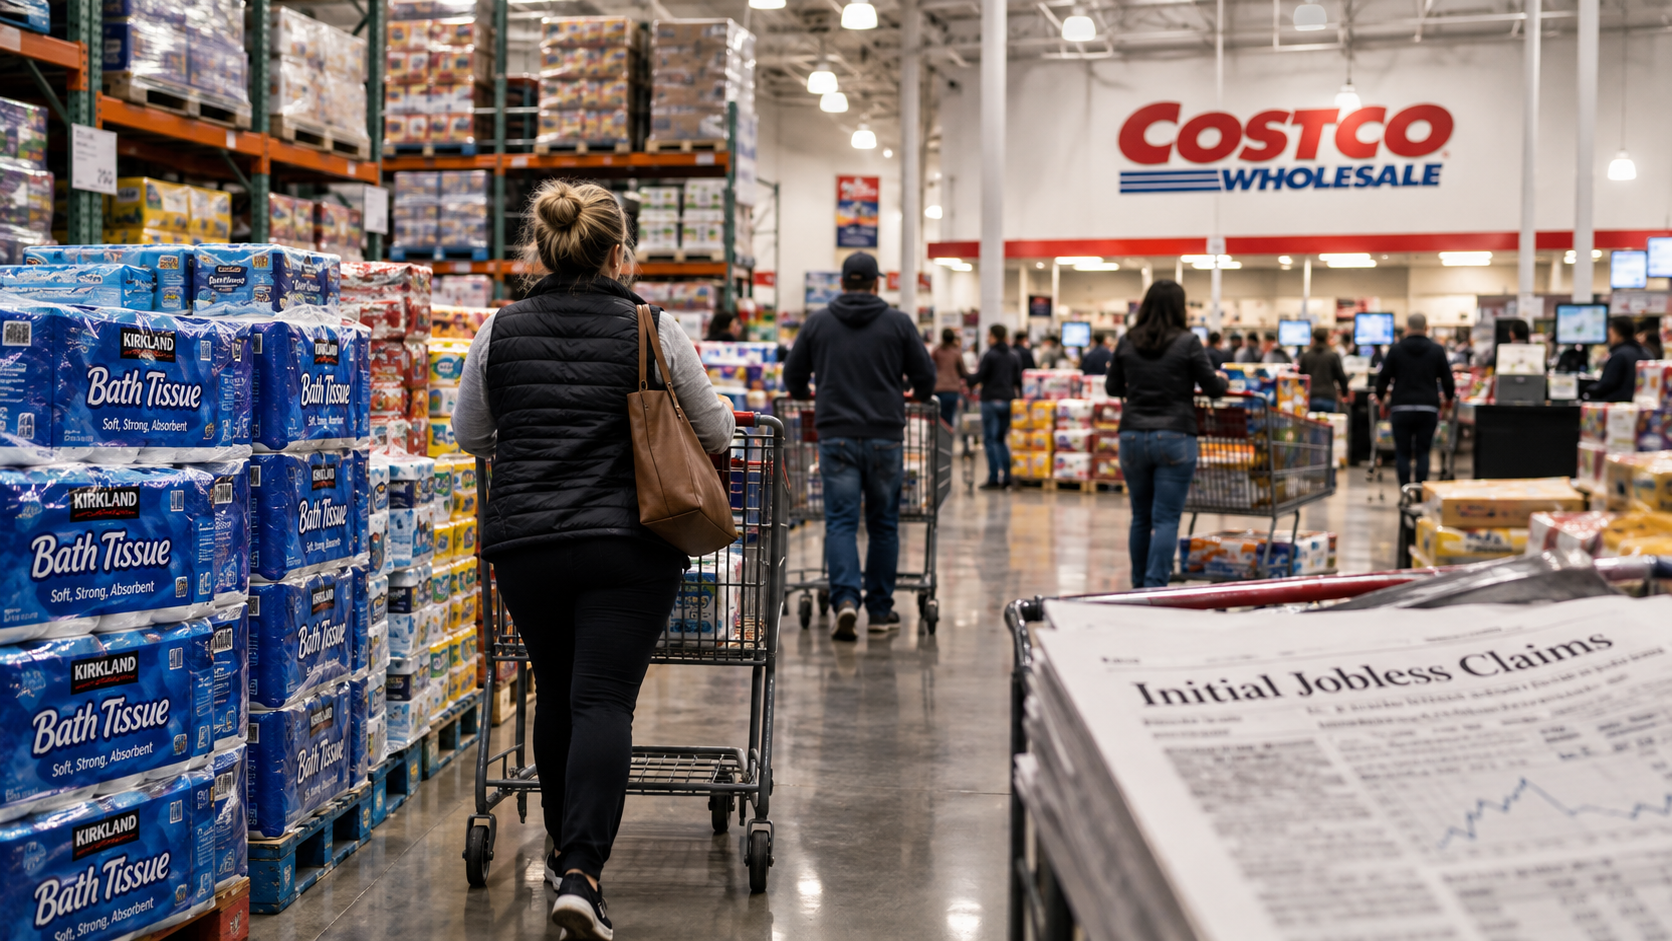
Headline data delivered a clear case of late-cycle ambiguity on Thursday. Initial jobless claims dipped below the 200,000 waterline to 197,000, while Costco beat top- and bottom-line expectations for its fiscal fourth quarter. The consensus narrative will label this enduring consumer resilience. In reality, it reflects balance sheet entrenchment. Employers are hoarding the labor they already have, while households are defensively migrating their spending to protect margins. An economy can avoid stall speed without offering anyone a smooth ride.
Jobless Claims: The Stagnant Low-Hitch, Low-Ditch Trap
Initial applications for unemployment benefits fell to a seasonally adjusted 197,000 for the week ended September 19, coming in comfortably under the 201,000 consensus estimate. Backward revisions alter the optical trajectory. The prior week tally was revised up from 196,000 to 198,000, turning the latest print into a 1,000-claim sequential drop rather than an expansion. The four-week moving average fell 1,750 to 202,250 against an upwardly revised previous baseline of 204,000.
Headline claims, however, are masking a structurally stagnant labor market. Low initial claims indicate low layoff velocity, but they say nothing about hiring absorption. When gross hiring freezes, displaced workers face extended jobless spells, a dynamic visible in continuing claims. Insured unemployment climbed to 1.719 million for the week ended September 12 from a revised 1.717 million.
Seasonal adjustments around late-September holidays also frequently flatter headline claims, muting volatility before fourth-quarter staffing swings kick in. For households, retaining a paycheck preserves baseline purchasing power. For the unemployed, an immobilized hiring market turns every search into an uphill slog. Policymakers interpreting sub-200,000 claims as proof of organic labor tightness are confusing reluctance to fire with willingness to hire.
Costco: Wallet-Share Cannibalization, Not a Demand Boom
Costco fourth-quarter print, spanning 16 weeks through August 30, generated $95.723 billion in total revenue against Zacks expectations of $94.82 billion. The top-line split underscores the operational engine: $93.873 billion in net merchandise sales alongside $1.850 billion in membership fees, the latter expanding roughly 7.3%.
Reported diluted earnings came in at $6.75 per share, up from $5.87 a year ago. The outperformance requires scrutiny. Costco booked a nonrecurring 15-cent net benefit from retroactive tariff refunds after partially passing savings through to members. Strip out that fiscal windfall, and operational EPS lands at $6.60. While still clearing the $6.48 consensus by 12 cents, the quality of the beat narrows once one-off customs relief is removed.
Metric | Q4 Performance | Context and Analytical Limits |
|---|---|---|
Total Revenue | $95.723B | Beat $94.82B consensus, includes $1.850B membership fees |
Adjusted EPS | $6.60 (vs. $6.75 reported) | Backs out a 15-cent one-off net tariff refund benefit |
Clean Comps (ex-gas/FX) | +6.7% Total (+7.2% US) | Reflects defensive trade-down volume, not higher unit expansion |
Digital Sales | +19.8% | Logistics leverage offsetting physical basket moderation |
Gross Margin | 11.02% of net sales | Slipped 11 bps from 11.13%, confirming retail price investment |
Operating Margin | 3.97% of total revenue | Up from 3.88%, sustained entirely through SG&A overhead discipline |
The market will read a 6.7% clean comparable sales growth print as proof of an unshakeable consumer. The structural reality is counter-cyclical. Warehouse clubs thrive late in the cycle because middle- and higher-income cohorts actively trade down. Surging club volume is an indicator of household balance-sheet defense, not discretionary expansion.
Furthermore, Costco merchandise gross margin slipped 11 basis points to 11.02%, confirming that even dominant scale operators must absorb vendor inflation and reinvest margin to defend unit throughput. Operating margin expanded to 3.97% only because disciplined overhead control outpaced merchandise margin pressure.
The Synthetic Signal: Late-Cycle Defensive Realignment
Costco shares barely moved after hours, edging down 0.13% to $895.32 following a 0.91% decline in the regular session. Extended-hours chop is an observation, not an indictment. Similarly, while the dollar firmed alongside the claims release, attributing macro exchange-rate moves to a single weekly labor statistic misreads global capital flows.
The critical flaw in pairing these data points is temporal and analytical. Weekly claims offer a near-real-time pulse of domestic termination notices, whereas Costco results capture a backward-looking 16-week cycle concluding in late August. Reading them as evidence of unbridled economic health mistakes defensive hunkering for organic vitality. Payroll preservation prevents outright contraction, while discount bulk-buying could stretch the real purchasing power of squeezed wages. The real test is not whether shoppers can keep warehouse registers ringing, but whether private companies can justify new capital expenditure and hiring once margin defense reaches its mathematical limit.
Sign in to leave a comment and join the discussion.
Sign Up Free