Introduction
As many of you know, North America is rewiring its supply chains.
This itself is fascinating. But what makes it even better is that this is a multi-decade shift: factories are moving closer to home, Mexico has become America's workshop, Canada wants to attract capital again, and the United States is building power plants, manufacturing facilities, and data centers at a pace we haven't seen in generations.
Most coverage focuses on the obvious winners, like industrial REITs and construction companies. I agree that these areas are great, but I want to focus on something else today.
Everything that gets built needs two things. First of all, it needs goods moving in and out. It also needs energy. And in North America, a surprisingly large part of both runs through a handful of networks that can never be rebuilt.
And whenever a "forced" demand trend meets limited supply, you know I get really excited.
In this article, I'll give you my view on the big picture. Then, I'll dive into two companies I find fascinating: Canadian Pacific Kansas City (CP), which yields less than 1%, and Kinder Morgan (KMI), which yields close to 4%.
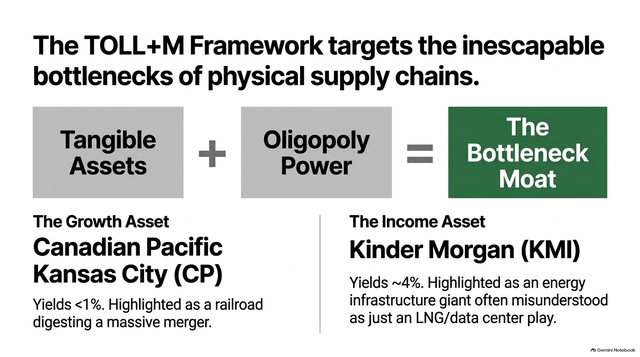
Both are well-known, especially KMI. But most coverage discusses CP as a railroad digesting an expensive merger and KMI as an LNG and data center play.
I see two companies that own the routes connecting three countries. And, as we'll see, both run straight through the same few hundred miles of South Texas.
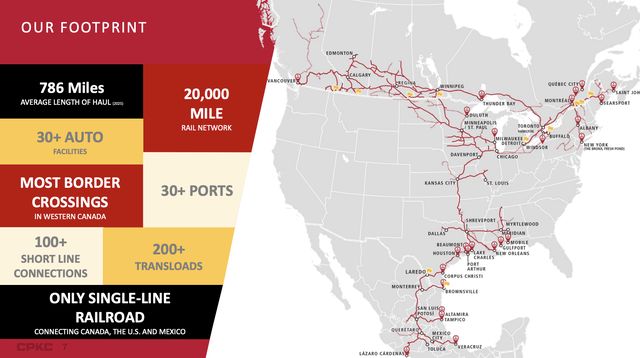
All of this is my way of saying that there's way more to these two companies than one might think when reading most "mainstream" research. So, in addition to discussing the Big Picture (which applies to way more stocks than these two), I'll spend time on two of my favorite picks here, one of which I own, and one of which I wouldn't mind owning if I had a bigger focus on income.
So, let's dive in!
Sign in to leave a comment and join the discussion.
Sign Up Free