The confession
I've been investing seriously for a long time. I built a screening system, I publish research for a living, and I have opinions about payout ratios that I'll happily share with people who didn't ask.
And I still got this one wrong for years.
Not wrong in the sense of losing money. Wrong in the sense that I was answering a question that had quietly stopped being the right one. For most of my investing life it was simple enough: will this compound?
That question isn't sufficient anymore. This year the capital I manage stopped being a scoreboard and started being a paycheck. It funds my household now. And in early 2027 I turn 59½, which is a real line in retirement-account planning, because the general age-based 10% additional tax on early distributions stops applying at that point.
Reaching that age doesn't make distributions tax-free, though. Treatment still depends on the account and the circumstances, so I'd rather state the rule narrowly than let it sound like a gate opening.
So the question changed. It's no longer only whether something compounds. It's what happens when I need cash out of it while it's compounding, and those aren't the same question. I want to walk you through why it took a couple of weeks of fairly obsessive modeling before I'd accept that.
What this article isn't
Two things, up front. It isn't a portfolio reveal. You won't find balances, allocations, position sizes, tax lots, cost basis or trades here. Every dollar figure below is a hypothetical illustration built for the argument, unrelated to any actual account.
It also isn't an argument that dividend growth beats high yield. I want to be blunt about that, because the internet has more than enough of those. The categories themselves turned out to be lazy. There's a continuum, and where a security sits on it matters less than whether it fits the job you need that slice of capital to do.
I'm not abandoning income investing. I'm trying to get far more precise about what good income investing actually means for someone in my position.
The catalyst
David L. Bahnsen published Profit from the Profit: The Past, Present & Future of Dividend Growth Investing through Post Hill Press on August 25, 2026. Somebody sent me two pages of it while I was already deep in this problem.
The pages sit two hypothetical retirees side by side. One pulls a fixed dollar amount out every year through a brutal early return sequence and watches the account go to nothing. The other takes only the dividend stream, which starts smaller but grows, and finishes with principal intact and a far better total economic result.
I'm deliberately describing those pages rather than reproducing them. They're his work, his numbers and his sequence, and if the argument interests you, the book is where it belongs.
Here's what I want to be honest about, though. My first reaction was probably the one he was going for. My second reaction, about an hour later, was skepticism.
The comparison proves something narrower than it appears to prove. It shows what happens when withdrawal mechanics collide with a bad return sequence. It doesn't show that dividend payers outperform, that distributions can't be cut, or that principal is somehow sacred. The phrase "not invading principal" bothered me in particular, and I'll come back to it.
So I did the only thing that ever settles it for me. I built my own version.
The mechanism nobody explains well
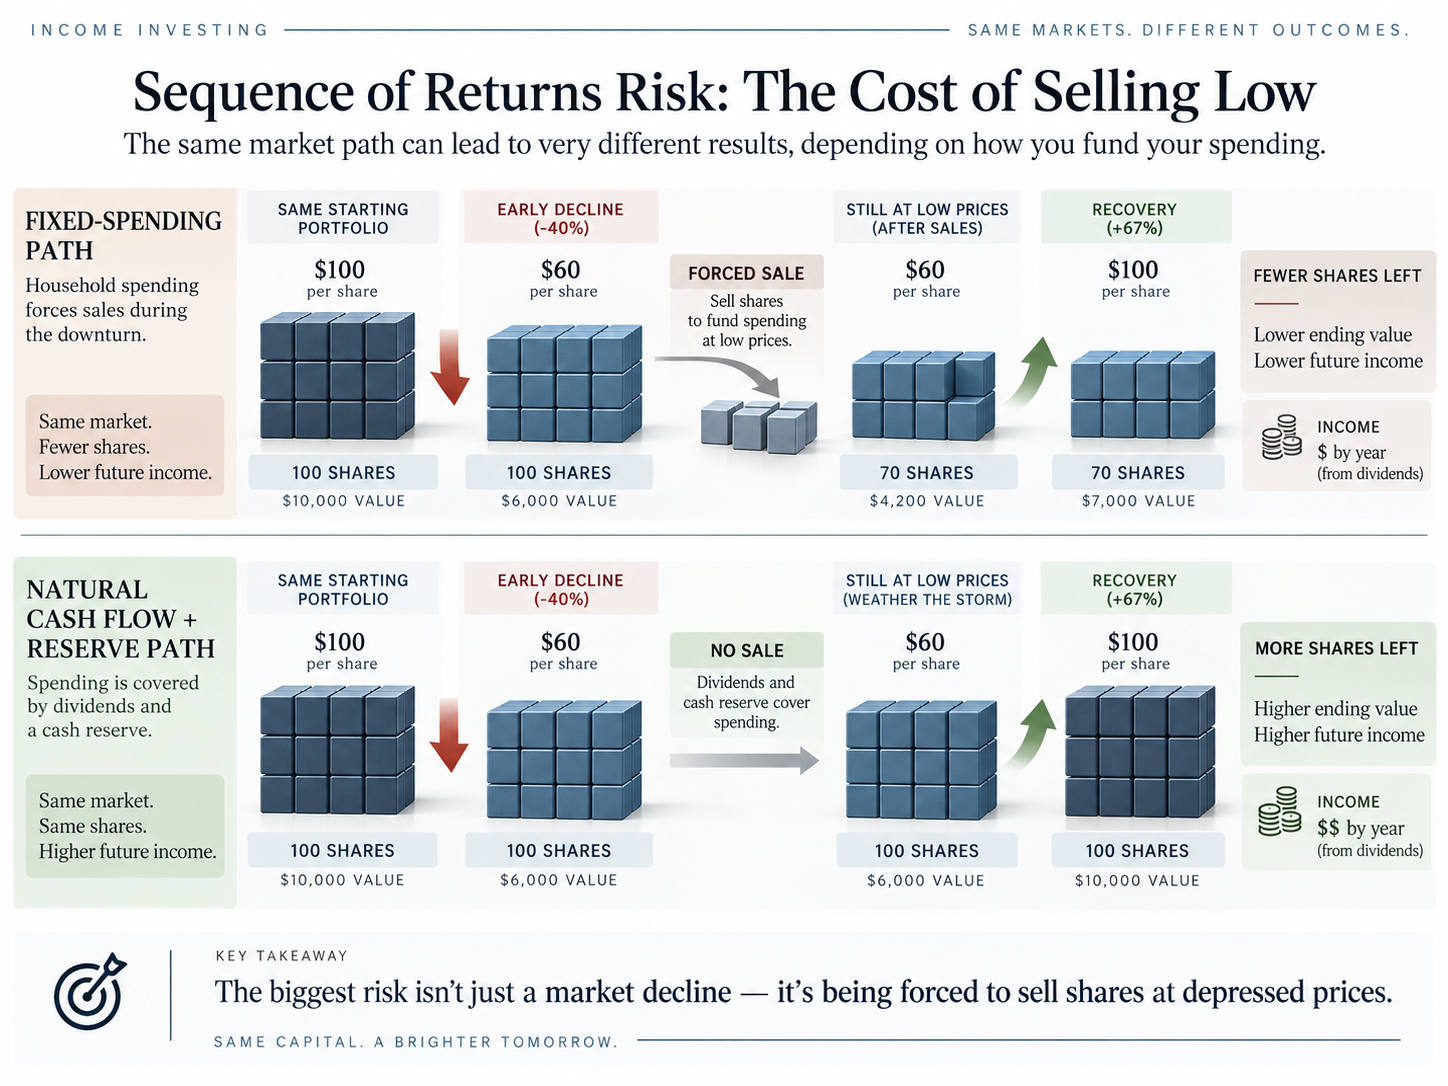
Sequence risk deserves a plain-English definition, because it's the most under-explained idea in retirement investing.
Start with a lump sum and no cash moving in or out. Order is irrelevant there, because the same set of returns in any sequence lands on the same ending value. The moment money starts flowing, that stops being true, and it stops being true in opposite directions depending on which way it flows.
While you're contributing, weak returns early are quietly helpful, since you accumulate more shares before the recovery. While you're withdrawing, weak returns early can be permanently destructive.
Vanguard's Principles for Retirement Income puts the mechanism plainly. When losses land early, the withdrawals a retiree has to make anyway shrink the base of assets left to ride the rebound, and the impairment is permanent. You sell shares at depressed prices, those shares are gone, and they aren't there when the market comes back.
Notice what's doing the damage. Not the decline itself, but the forced sale during it.
That distinction is the whole article, so let me say it once more in the way it finally landed for me. If the portfolio produces enough cash on its own that I never have to sell into a bear market, the channel doing most of the damage narrows sharply.
It doesn't seal shut, though. Dividends get cut in exactly the markets where you were counting on them, and a portfolio that stops throwing off enough cash turns you back into a seller at the worst possible moment.
That's what "sleep well at night" means to me, concretely. Not high yield. Not low volatility. Not being a forced seller.
My own illustration
I built a model with one variable changed and everything else held identical. Same starting capital, same portfolio, same starting yield, same dividend growth, and critically, the exact same sequence of price returns. Only the withdrawal policy differs.
The setup: $1,000,000 hypothetical starting portfolio, fifteen-year horizon, 3.0% constant inflation assumption. The portfolio begins at a 4.0% dividend yield with dividends per share growing 5.0% annually, held constant so we're isolating one thing only.
Policy A, fixed spending. The household needs $50,000 in the first twelve months, rising 3% annually with inflation. Dividends fund what they can, and any shortfall gets met by selling shares. A surplus would get reinvested, though in this run the dividends never once exceed the spending.
Policy B, natural cash flow. Spend the dividends. That's it. No shares are ever sold.
The return sequence is constructed by me and deliberately punishing, front-loaded with damage: -18%, -12%, -22%, 21%, 9%, 6%, -5%, 14%, 11%, 7%, -8%, 13%, 10%, 6%, 9%. That compounds to a cumulative price gain of about 33.7% over the full period, roughly 2.0% annualized.
Those are price returns only, which matters more than it sounds. If you use a total-return series that already includes dividends and then add dividends on top, you've counted them twice and your conclusion is fiction. Most illustrations of this type get that wrong.
Here is the result.
Sign in to leave a comment and join the discussion.
Sign Up Free