CCAT
Supply ChainEnergy Sectorinterest ratesIndustrial StocksShipping Costs, Energy Credit, and the Squeeze on Operating Margins
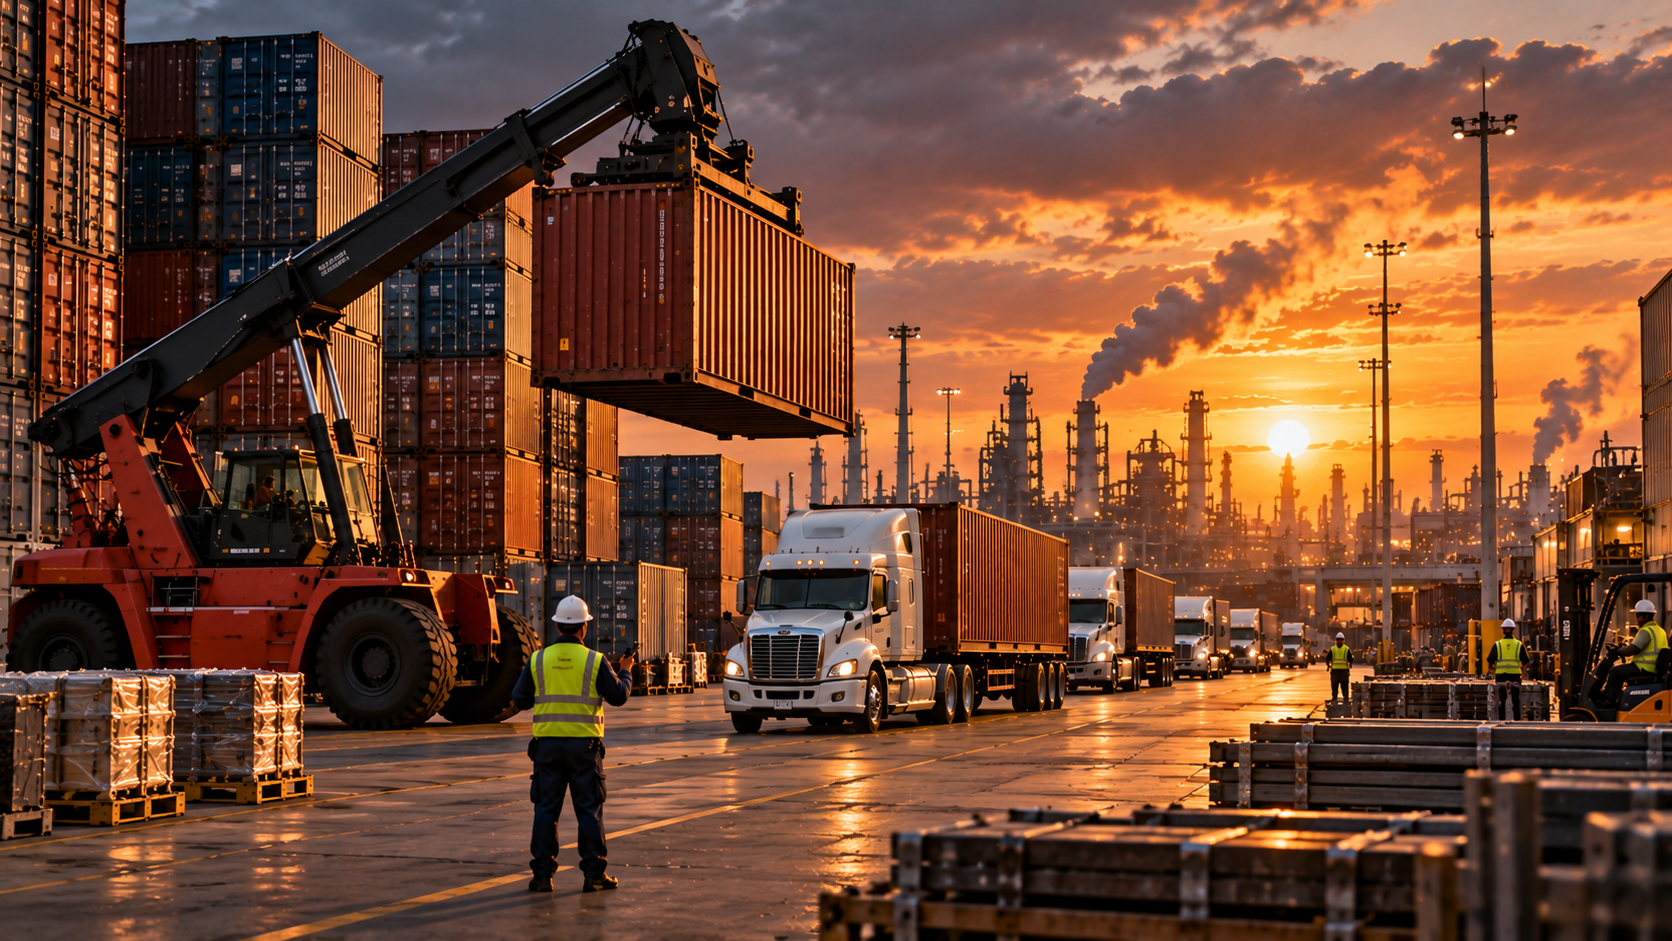
- Middle-market industrials face simultaneous pressure from elevated ocean freight, higher borrowing costs, and volatile energy, favoring large diversified producers over smaller peers
- Ocean freight is structurally higher - Drewry WCI $4,585/40ft (Oct 22); Shanghai-LA $8,007; Shanghai-NY $10,166; blank sailings rose 2 to 8 WoW, East Coast ~$10k/container
- Credit squeeze for mid-tier firms - working capital costs ~6-7%; Oct auto loans avg 6.81%, avg financed $44,664, 84+ month loans 25.5%, avg payment $823, total interest ~$9,938/vehicle
Oct 29, 202611:43 AM ET20
The middle class of industrial operators faces simultaneous pressure from elevated ocean freight costs, higher borrowing rates, and volatile energy expenses. These three forces are reshaping the economics of production and assembly across the commodity supply chain, favoring large, diversified producers while compressing returns for smaller competitors. Ocean freight costs have surged since February when geopolitical tensions disrupted shipping through the Strait of Hormuz. The Drewry World Container Index, the standard procurement benchmark, sat at $4,585 per 40-foot container as of October 22. Shanghai to Los Angeles routes cost $8,007 per container, up 2% over the previous week. Shanghai to New York reached $10,166. The Asia-Europe corridor remains under sustained pressure, with Shanghai to Rotterdam at $3,632 and Shanghai to Genoa at $4,152, up 5% week-over-week. These are not the momentary spikes of 2021-2022. Carriers are managing capacity deliberately through blank sailings (scheduled service cancellations) to maintain pricing power. In late October, eight blank sailings were scheduled for Asia-Europe services, compared with two the previous week, indicating carriers view the high-rate environment as structural, not temporary. For companies importing manufactured goods or raw materials, these rates directly increase the cost basis of inventory. A typical 40-foot container from Asia to the US East Coast now costs roughly $10,000. The container-to-FEU conversion means spot rates moving from historical norms of $2,000-$3,000 to $4,500+ represents a 100-150% increase in a single input cost category. Procurement teams cannot absorb that through margin compression alone. The cost gets passed to end customers or capital investment gets deferred. The second pressure is credit cost. The Federal Reserve held interest rates steady at 3.75-4% this week, but the immediate borrowing environment for mid-market companies has tightened significantly. JD Power forecasts indicate October 2026 average auto loan rates hitting 6.81%, the highest October level since 2023. New-vehicle buyers financed a record average of $44,664 in Q3 2026, with loans exceeding 84 months now accounting for 25.5% of all financed purchases, up from 21.8% in Q3 2025. Average monthly auto loan payments reached $823 in October, a record high. Total interest on financed new-vehicle purchases has climbed to a record $9,938 per vehicle, even as the average transaction price declined slightly. This credit tightening extends beyond consumer auto lending into working capital financing for businesses. A manufacturer that extends 60-day payment terms to customers while paying suppliers in 30 days requires bridge financing to fund inventory and receivables. When supply chain financing or trade credit lines renew at higher rates, cash flow models change immediately. Companies with sub-5% cost of capital have shrunk their pool to large conglomerates and companies with strong cash generation. Mid-tier industrial firms now face 6-7% effective rates on working capital financing. The third force is energy. US crude oil has oscillated sharply. After declining toward $90 per barrel in early October, WTI crude moved back above $102 by late October as geopolitical tensions reignited peace negotiation signals. Brent crude traded in the $100-$115 range. Natural gas has weakened, with Henry Hub prices around $2.76 per MMBtu as of late October, down from elevated levels in September. However, crude oil volatility remains the dominant concern. For any business with energy exposure in production, transport, or heating, the current range of $100-$105 per barrel means carried costs vary by thousands of dollars per week depending on hedging posture. Mining and heavy equipment manufacturers show the clearest beneficiary pattern. The US rig count climbed to its highest level since May 2024 in late September 2026, driven by elevated crude prices. The mining machinery and equipment market g
Sign in to leave a comment and join the discussion.
Sign Up Free