Introduction
Last week, I got a question from a member that I haven't been able to stop thinking about.
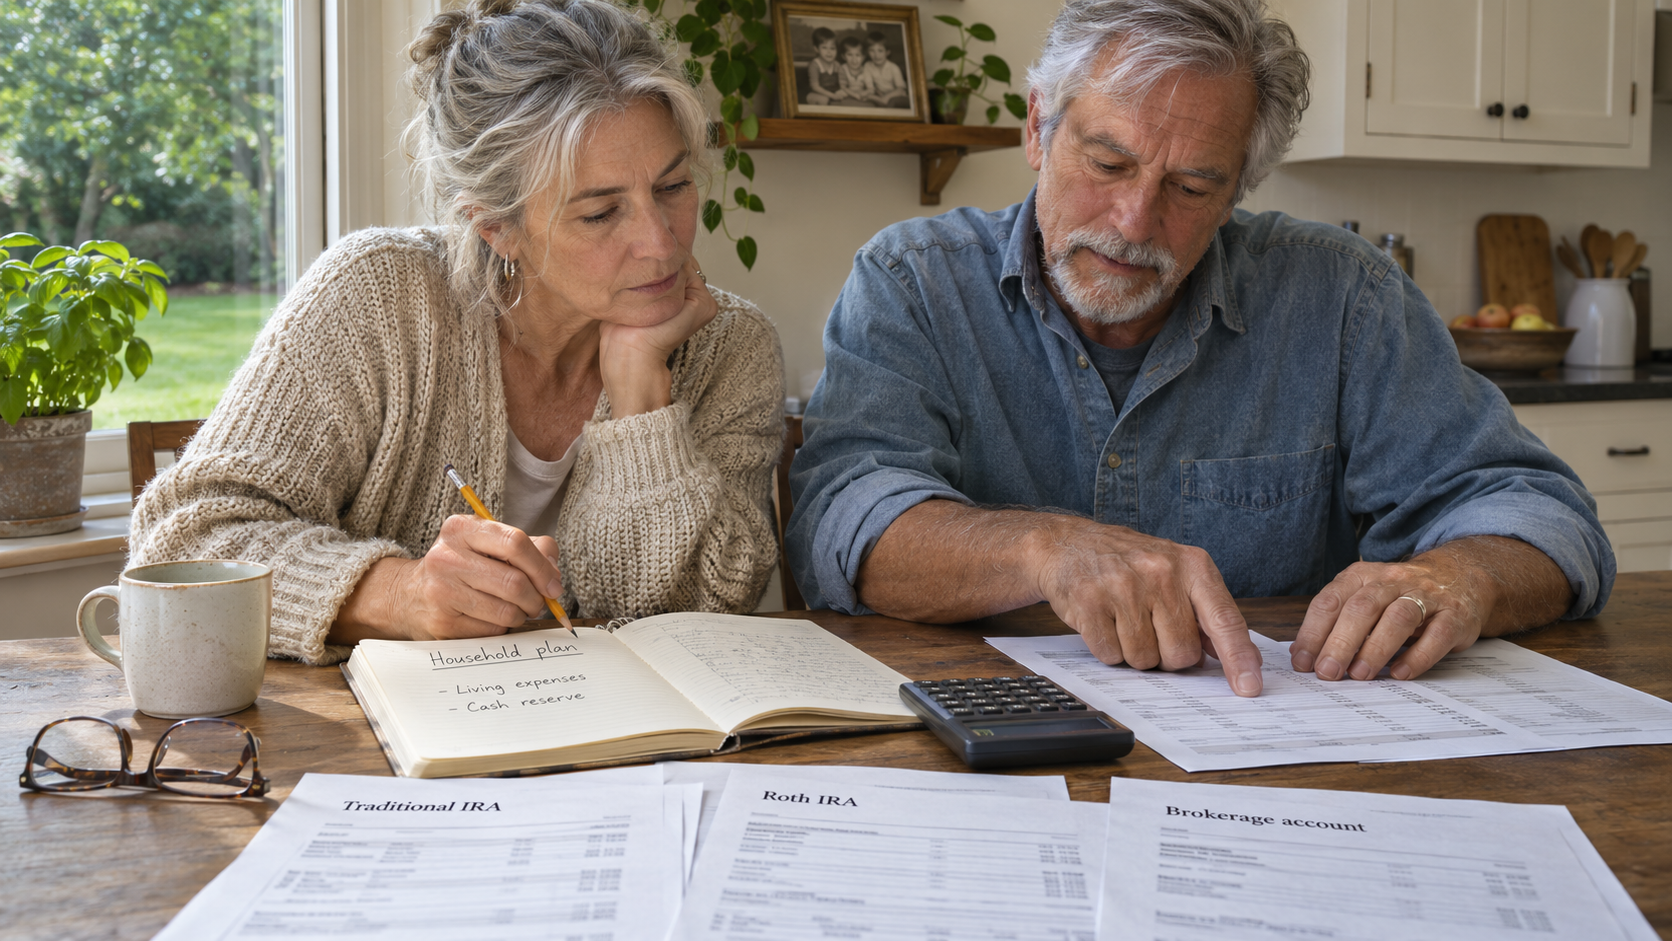
Hello Leo, I have a basic question that in the end may not be so basic. I have been reviewing my portfolio in depth recently […] and I'm trying to understand position weighting. How does one go about determining each positions weight? I'm wondering if positions are a target or a result. Given that I am 62 retired/wife 65 working with his & hers IRA's, Roth's, and brokerage accounts. I do barbell the positions but struggling to understand weighting strategy. - Erik
Erik is right. It's not basic at all - far from it.
As many of you know, I spend most of my time on stock picking, including the Big Picture assessment that comes with it. Which companies to own, why, and at what price. That's also what most investment research is about.
There's just one problem.
Picking the right stock is only half the job. The other half is deciding how much of it to own. And that half is where most of the real damage (and most of the real wealth!) happens.
Think about it: a 2% position that doubles adds 2% to your portfolio. A 20% position that gets cut in half costs you 10%. I've had both things happen to me.
So, in this article, I'll answer Erik's question properly. I'll explain why every portfolio has three weights (and why most investors only look at one), how I'd size positions by the job they do, and how I'd weight the same stocks at 31, 50, and 65.
I'll also show you my own portfolio through this lens, including the parts that don't look great.
And yes, there are stock ideas along the way - some fresh ones!
So, let's dive right in!
Sign in to leave a comment and join the discussion.
Sign Up Free