The conventional narrative holds that the modern economy is being squeezed by simple scarcity. Wall Street analysts point to diesel cracks, grid interconnection queues, and semiconductor tariffs as temporary frictions that will clear once capital expenditure catches up with demand. This consensus is comforting because it implies that higher prices are just a prelude to higher supply. The reality is far more uncomfortable.
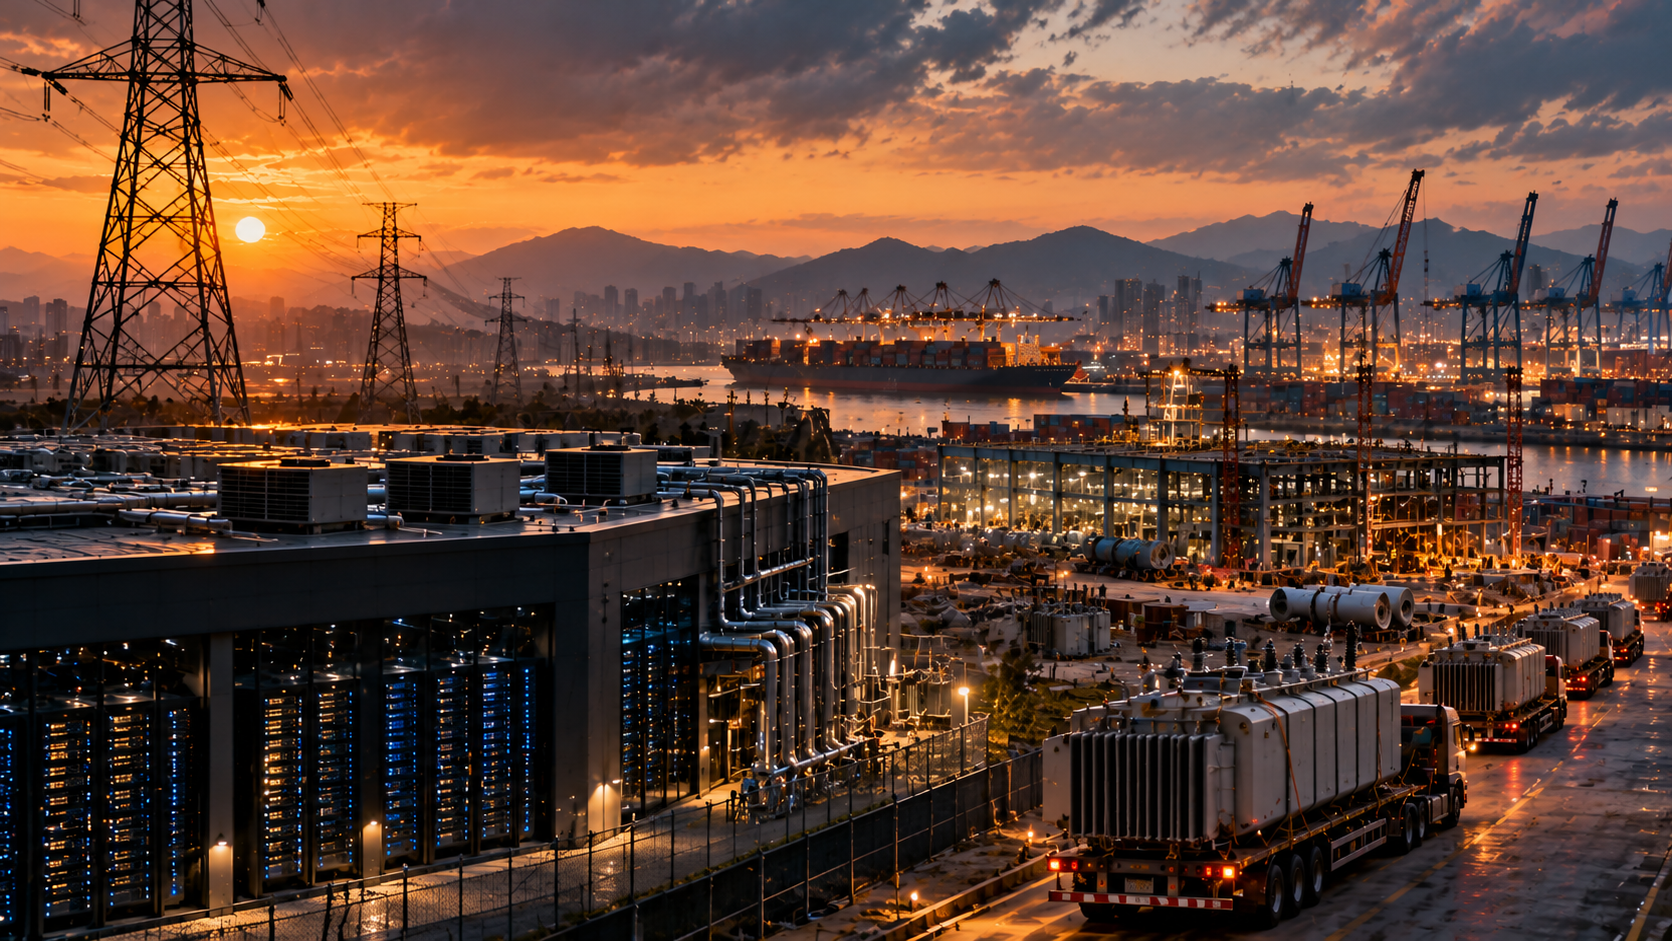
The physical constraints governing trade and technology are not bottlenecks on the road to expansion. They are the permanent walls of a fragmented global economic order. Operators and allocators who plan for a return to frictionless globalization are building models on foundations that no longer exist. Consider the energy and power dynamic that are the current obsessions in financial markets. The dominant view assumes that artificial intelligence data centers are an insatiable beast devouring every available megawatt, driving utilities to the brink and forcing a massive capital spending super-cycle in power generation. The standard takeaway for investors is to buy independent power producers, turbine manufacturers, and transmission line builders while shorting anything exposed to high electricity bills. This story misses the structural contradiction at its core. Hyperscalers are rushing to lock in long-term power purchase agreements at precisely the moment when algorithmic efficiency and hardware optimization are bending the power-to-compute curve downward.
The real insight is that the data center power crunch is a temporary over-building trap disguised as a shortage. Semiconductor architectures are shifting rapidly from brute force training models toward highly efficient inference engines that require a fraction of the power per token. At the same time, utilities are committing billions of dollars to interconnect massive campus loads under contracts with twenty-year take-or-pay terms. When the efficiency gains hit commercial scale over the next twenty-four months, hyperscalers will find themselves holding expensive power purchase agreements for capacity they no longer need, while utilities are left with transmission upgrades paid for by captive residential ratepayers.
Operating executives caught in this cycle face a distinct trap. Industrial manufacturers and commercial enterprises are currently competing with data center developers for electrical transformers, switchgear, and substation capacity, driving up capital costs across the board. Factory owners assume they must electrify and automate their operations immediately to keep pace with productivity trends, locking in equipment purchases at peak cyclical prices. The contrarian move for an operator is to pause major electrification capital expenditures that rely on scarce grid access. Instead, focus on local energy optimization, behind-the-meter co-generation, and asset utilization that squeezes more output from existing power footprints rather than chasing speculative expansion in grid-constrained zones.
Capital allocators must re-examine the infrastructure thesis through the same lens. Buying power generation and grid equipment suppliers on the assumption of uninterrupted secular demand growth ignores the cyclical vulnerability of utility balance sheets. If data center demand growth moderates due to compute efficiency gains, regulated utilities that expanded their rate bases on aggressive load forecasts will face regulatory pushback and stranded asset write-downs. Allocators should gradually rotate away from consensus picks in high-voltage equipment and into businesses that control localized, brownfield energy assets with flexible off-take agreements that do not depend on hyperscale expansion.
The trade and logistics sector reveals a similar illusion. The prevailing wisdom views US tariffs and reshoring policies as a successful industrial strategy that is bringing manufacturing back to North America and building a resilient domestic supply chain. The financial media celebrates factory groundbreakings in Arizona and Ohio as proof that globalization is reversing into a secure regional bloc. This framing ignores the balance-sheet reality of the industrial transition. This is not an “everything transition.” Moving 100% of production out of low-cost Asian ecosystems and into domestic facilities was never the aim.
Quite a bit of domestic manufacturing is shackled by structural cost disadvantages that tariffs cannot cure. Industrial electricity prices in the United States are climbing due to grid congestion and data center competition, while labor costs remain structurally higher than in competing jurisdictions. When an American manufacturer replaces an imported component with a domestic alternative, the input cost could double. Mid-market operators who swallow these higher input costs to maintain domestic sourcing find their margins compressed unless they possess extraordinary pricing power. Most do not. They are absorbing a stealth consumption tax that weakens their competitive position against foreign rivals who continue to source from unconstrained global supply chains.
The allocator angle on reshoring is equally distorted by political wishful thinking. Wall Street treats domestic industrial policy as a pure growth driver, assuming that subsidies and border protection guarantee earnings expansion for US capital goods firms. The reverse is often true. Companies burdened with domestic manufacturing footprints lose export competitiveness as their cost structures detach from global clearing prices. Allocators should underweight pure-play domestic industrial suppliers whose margins depend on trade protection, and overweight agile supply-chain integrators who maintain global sourcing optionality while diversifying to low-friction jurisdictions like Mexico or Vietnam.
Inflation provides the final piece of this contrarian puzzle. Central banks and financial markets remain fixated on cyclical indicators, treating persistent core inflation as a lingering hangover from pandemic fiscal stimulus that higher interest rates will eventually cure. This diagnosis is fundamentally flawed. The current inflation regime is driven by the permanent cost of economic fragmentation. Maintaining redundant supply chains, duplicating semiconductor manufacturing ecosystems, and securing fragmented energy corridors require massive amounts of capital expenditure that yields zero consumer utility. It is an economic tax paid to achieve geopolitical insurance.
Because this fragmentation is permanent, interest rate policy is operating on the wrong levers. Raising the federal funds rate slows down housing and consumer discretionary spending, but it does nothing to lower the cost of building a domestic semiconductor fab or securing a diesel supply chain. In fact, higher interest rates actively hinder the physical capital investments required to resolve supply bottlenecks, making the structural inflation problem worse. Central banks are trapped in a monetary straitjacket, trying to solve a structural supply crisis with demand-destruction tools.
For operators, this means margin pressure is not a temporary valley to endure until monetary policy pivots. It is the new baseline of commercial life. Businesses that survive and compound through this environment are those that ruthlessly audit their cost structures for non-productive overhead and renegotiate customer contracts to include dynamic input-cost adjusters. If an operator cannot pass along the real cost of supply chain redundancy and energy friction immediately, the business is effectively subsidizing its customers' operations out of its own equity.
For allocators, the investment implications require a complete break from traditional index-weighted thinking. Passive equity portfolios are heavily concentrated in technology and consumption models built for an era of zero-friction globalization and falling input costs. As the true cost of economic fragmentation hits corporate earnings, the divergence between headline index performance and underlying cash-flow durability will widen dramatically. Capital preservation demands owning real assets with pricing power, businesses with short cash-conversion cycles, and entities that profit from friction rather than suffering from it.
The illusion of easy fixes and predictable mean-reversion is the greatest hazard in contemporary markets. The constraints governing energy, trade, and technology are not anomalies to be waited out. They are the structural architecture of the new economic reality. Those who recognize that the old rules are dead will reallocate capital and restructure operations before the rest of the market realizes that the bottlenecks are here to stay.
Sign in to leave a comment and join the discussion.
Sign Up Free