AARCC
AARES
BBX
JJPM
AAMZN
MMSFT
GGOOGL
MMETA
OORCL
NNVDA
VVST
AI InfrastructurePrivate CreditBusiness Development CompaniesAlternative Asset ManagementAI Needs $6.3 Trillion - KKR Just Told Us Where The Money Goes
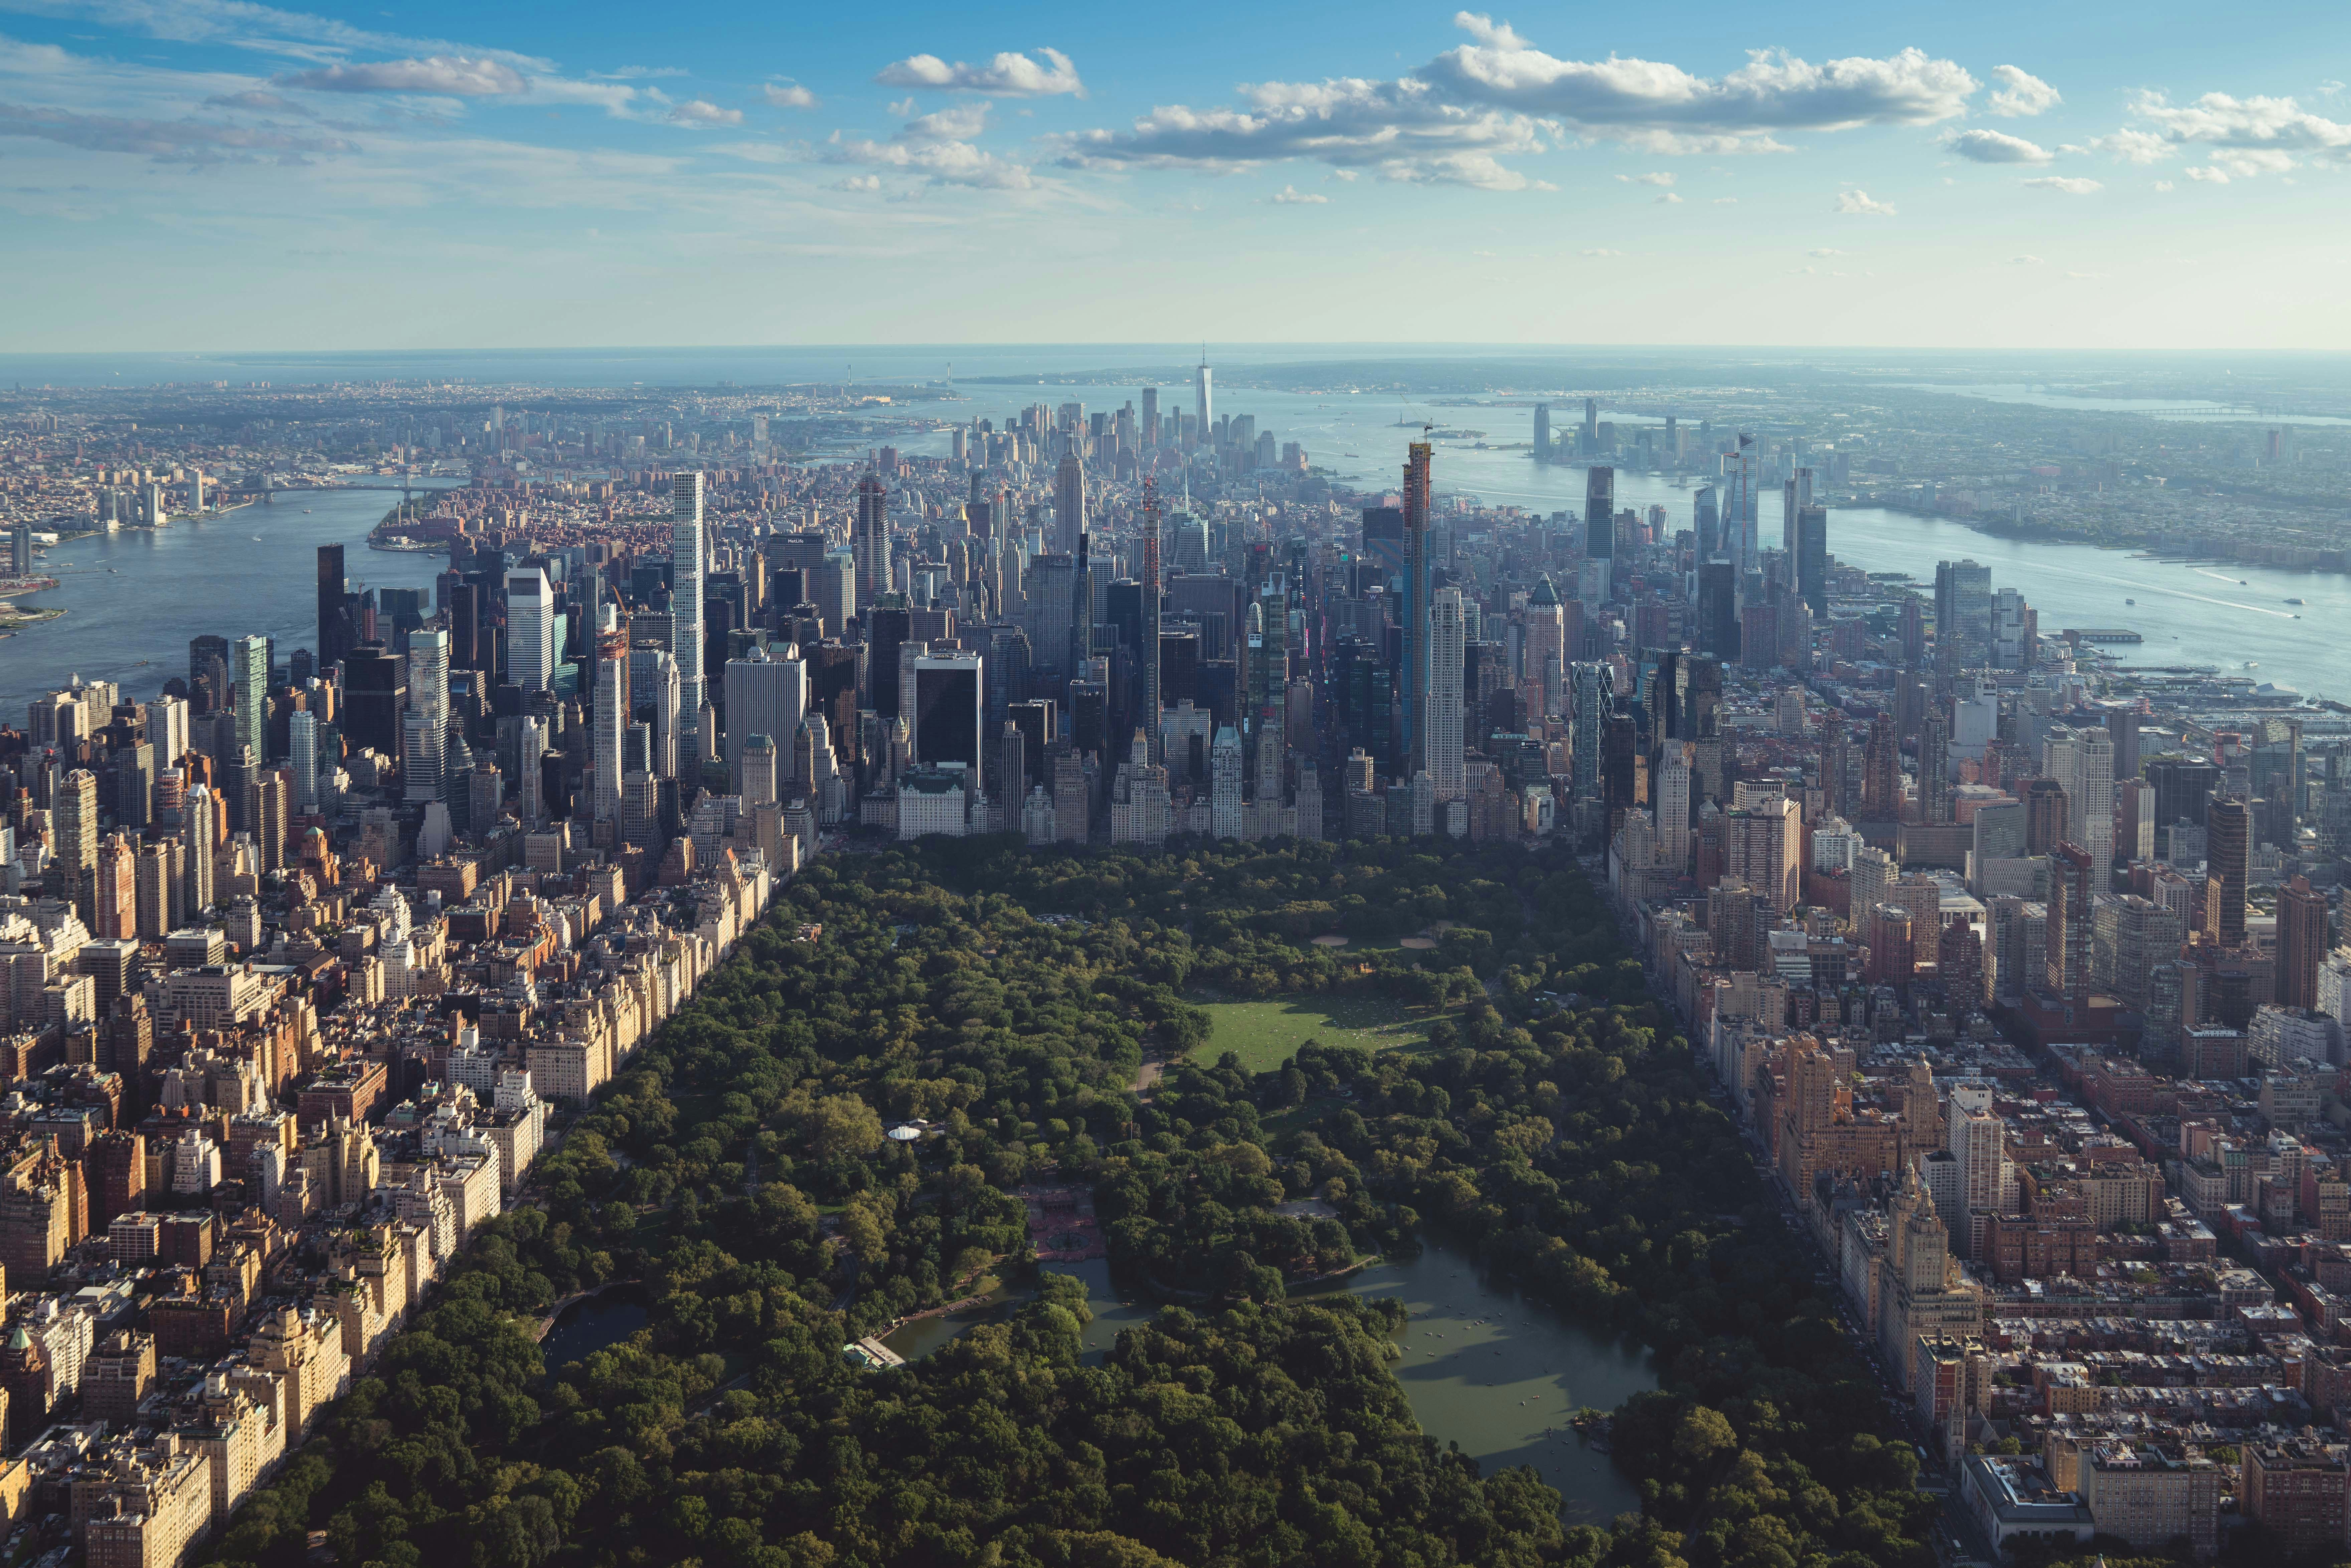
- KKR projects $7.6-8.0T of AI infrastructure capex through 2030, leaving a $6.3T funding gap after hyperscalers' estimated ~$1.7T of additional public IG issuance
- Private IG, asset-based finance, infrastructure debt and new securitizations must fill the gap - AI-linked issuance was ~$189B in 2025 and APO/BX arranged a reported $35B Anthropic deal
- AI-related debt equals ~6.3% of US IG direct bonds or ~11.6% of JPM's liquid IG, and roughly 40% of S&P revenue is AI-linked, concentrating exposure in chips, power, cooling and leases
- BDC mechanics matter - example: $100 equity plus $100 debt lent at 11% yields $13 NII or 13% return on equity; monitor price vs NAV, non-accruals cost vs fair value, core earnings vs GAAP
- Rising rates help floating-rate lenders but strain weaker borrowers - CCC/B spreads hit 3.5x; software is >20% of corporate private credit (possibly ~30%), raising idiosyncratic credit risk
Oct 14, 20263:03 PM ET90
Introduction As many of you know, I spend a lot of time reading what the biggest capital allocators in the world tell their own clients. Last month, KKR's (KKR) Credit & Markets team published its 3Q26 market review, "Let There Be Compute!" I believe it is one of the most useful documents written on the AI buildout this year, as dramatic as that may sound. Generally speaking, most AI coverage comes from the equity side. This report asks a different question. Who pays for all of this? And who gets paid if the plan changes? As AI needs a ton of money, we need to be on top of things on the funding side of things as well. That matters for us. Many MSA members own BDCs (business development companies) for income, and many own or want to own alternative asset managers for growth. It just so happens that both sit right in the middle of the financing machine KKR describes. In this article, I'll walk you through the key findings, explain how BDCs and asset managers actually make money, and apply it all to four names I like, including valuation and sizing. I'll also give you a checklist you can use on any BDC you own. So, let's dive in! The Gold Rush Lesson KKR opens with California history. In 1849, the resource was gold and the tool was a pan (let's keep it simple in this example). In 1892, the resource was oil and the tool was a derrick. In both cases, much of the lasting wealth went to the people who supplied the tools, financed the claims, and built the railways and pipelines. "The value was never just the resource; it was often the pipes that moved it." - KKR Credit & Markets It's the toll-road argument applied to finance. The third rush, according to KKR, is compute. And compute needs financial pipes. Now, comes the part where I justify the title of this article. The $6.3 Trillion Question AI infrastructure CapEx is projected at roughly $7.6 trillion to $8 trillion through 2030. The obvious way to fund that is investment-grade ("IG") bonds issued by the hyperscalers (Amazon, Microsoft, Alphabet, Meta, and Oracle). There's just one problem - a big problem. Most bond money is managed against an index, and no fund manager wants one company to become too large a part of it. KKR uses a 3% single-issuer weight as a practical ceiling. For context, the 29-year average for the biggest issuer in the IG index is 2.6%. Think of it like a dinner party. Everyone is happy to have a big guest. Nobody wants one guest eating 15% of the food. That's what would happen here: if the five largest hyperscalers all hit 3%, they alone would make up 15% of the IG index. KKR estimates the hyperscalers can issue roughly $1.7 trillion of additional public IG debt before hitting that ceiling. That leaves a gap of roughly $6.3 trillion. Some of that will come from the companies' own cash flow. The rest has to come from private IG, asset-based finance (ABF, lending against equipment, leases, and contracted cash flows), infrastructure debt, and structures that, in KKR's words, "may not even exist yet." It could look something like this: And here's the chart I think gets overlooked as well: It shows 12-month forward free cash flow. The semiconductor companies, the ones selling the "pans," are seeing free cash flow soar. The hyperscalers, the ones buying them, are seeing forward free cash flow fall toward zero and below. The biggest buyers of compute are running short on internal funding just as the bill gets bigger. That's one of the best demand signals for private credit I've seen in years. Also, the market is adapting. AI-linked issuance was roughly $189 billion in 2025 and has more than doubled year-over-year. In June, Apollo (APO) and Blackstone (BX) reportedly arranged a $35 billion private credit deal tied to chip financing for Anthropic. All of this means that when a capital-hungry industry runs out of internal cash, the firms that can write very large, customized checks gain pricing power. Whe
Sign in to leave a comment and join the discussion.
Sign Up Free